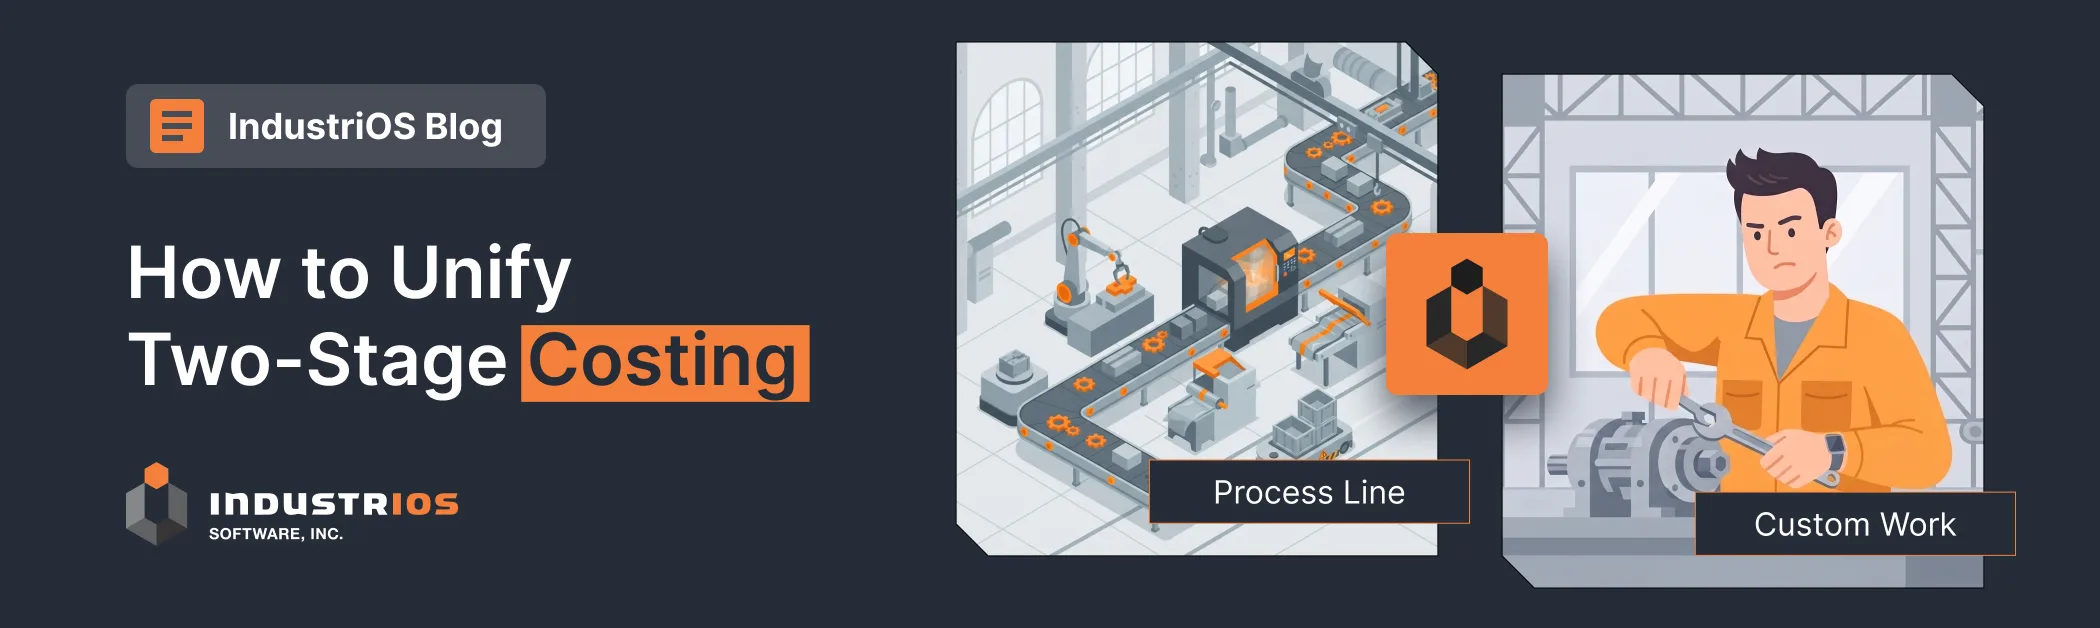
Two-stage costing is a job costing method for hybrid manufacturers. It carries the cost of the process stage (material, yield and line time) straight into the cost of the discrete job (die-cutting, routing, assembly and labour). The result is one unified job cost that reflects both stages, updated as work happens, not reconciled at month-end.
Because the cost of a hybrid job lives in two places:
Most teams only join the two at month-end. By then the job is done, and any margin leak is already baked in. Job costing effectively stops at the manufacturing stage.
The same gap appears in single-stage make-to-order work. Our guide to Job Costing in Make-to-Order Manufacturing covers the fundamentals.
At minimum:
Material: the raw material lots consumed by the process run.
Process yield: how much usable material the run produced, and what the scrap or waste cost.
Line time and labour: what the shared process line and its crew cost while making this job’s material.
Discrete stage costs: tooling, machine time and labour for the production work.
Overheads: allocated across both stages consistently.
For the wider cost picture, see Make-to-Order Manufacturing Costs: 9 Essential Types to Track. If imported materials feed your process line, Mastering Manufacturing Landed Costs explains how to capture their full cost.
Many hybrid manufacturers run on QuickBooks plus spreadsheets. QuickBooks has no manufacturing module, so cross-stage costing is done by hand: process costs are exported, re-keyed and matched to jobs before the books can close.
Every manual step adds time to month-end, and every re-keyed number is a chance for error. The close drags because the work that should happen as production runs is all saved up for the end of the month. The fix is costing that flows from the process run into the job automatically, so month-end confirms numbers you’ve already seen rather than discovering them.
You don’t have to leave QuickBooks to fix this. IndustriOS integrates with QuickBooks: IndustriOS handles production, inventory and job costing, while financial statements, payments and cash receipts stay in QuickBooks. If your financials run on Sage 300cloud, IndustriOS offers two-way integration, so transactions reach the back office without re-keying.
Map where each cost lives today. List the systems and spreadsheets that hold process and job costs. An ERP gap analysis is a structured way to do this.
Connect the process run to the job. Every job should know which process run, and which raw material lot, its material came from.
Roll costs forward automatically. Process costs should flow into the job as the material is consumed, not be re-keyed later.
Review margin while the job runs. Use live job cost against the quote to catch problems before shipment.
IndustriOS rolls process costs directly into discrete job profitability. One unified job cost reflects both the process yield and the production work, so you see true margin now, not at month-end.
Our brochure, Real Time Costing Across Both Stages, walks through the approach.
What is the difference between job costing and two-stage costing?
Job costing tracks the cost of each production job. Two-stage costing extends it back through the process stage that made the job’s material, so the job cost includes process yield and line time.
Why does process yield matter to job margin?
If a process run produces less usable material than planned, every job that draws from it costs more. Without the link, that loss shows up only as a month-end variance.
Can spreadsheets handle two-stage costing?
They can hold the numbers, but they need manual exports and re-keying, so the answer arrives after the job is done.
Can QuickBooks handle manufacturing job costing?
QuickBooks has no manufacturing module, so job costing across a process stage and a discrete stage is done manually, usually in spreadsheets. A manufacturing ERP that integrates with QuickBooks can take on costing while the financials stay where they are.
Does two-stage costing need a separate process ERP?
No. The point is one system covering both stages, so the costs don’t need joining up later.
Related reading: Hybrid Manufacturing: Shared Capacity Planning · End-to-End Traceability · Manufacturing Environments Explained
Download 1 of 11 Continuous
Improvement Templates